
Economy
Banks show resilience despite economic challenges – Afrinvest report

The 2022 Afrinvest Banking Sector Report has shown that commercial banks recorded modest improvement in all regulatory indicators despite daunting economic challenges.
The report, presented by Deputy Group Managing Director, Afrinvest West Africa
Mr Victor Ndukauba, showed that the banks beat all the prudential guideline limits set by the Central Bank of Nigeria, showing resilience and strength during the year.
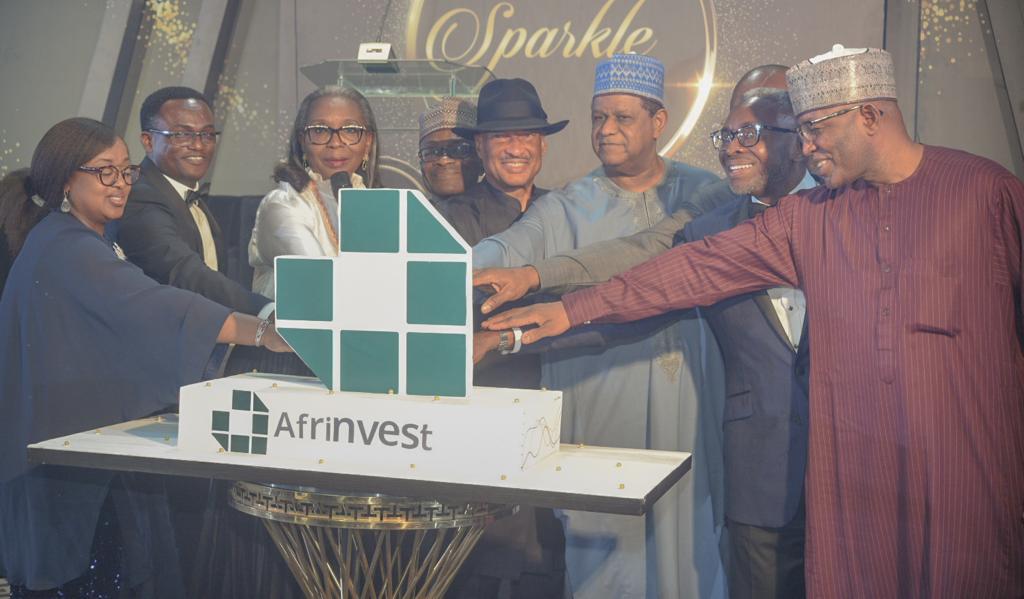
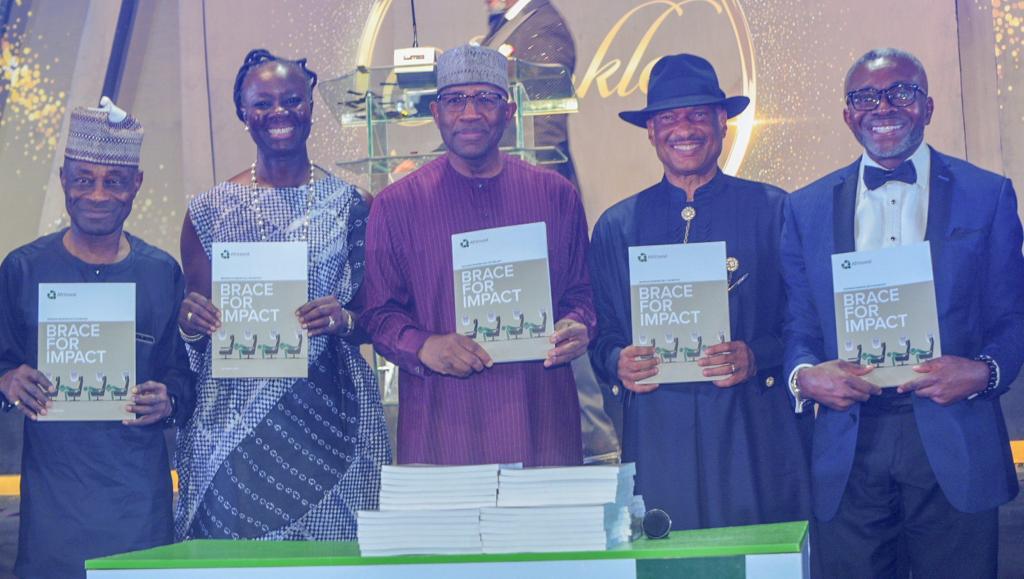
L-R: Chief Operating Officer, Afrinvest, Mrs Onoise Onaghinon; Deputy Managing Director, Mr Victor Ndukauba; former chairman, First Bank, Mrs Ibukun Awosika; Chairman, Afrinvest Asset Management, Mr Abdul-Rahman Esene; Chairman, Afrinvest, Mr Donald Lawson; former managing director, FSB Int’l Bank, Mr Mohammed Hayatudeen; Group Managing Director, Afrinvest, Mr Ike Chioke; Director General, Securities and Exchange Commission, Mr Lamido Yuguda, during the cutting of Afrinvest’s 27th anniversary cake and launch of it new logo in Lagos… on Wednesday
Its presentation was made at the launch of the 17th edition of the Nigerian Banking Sector Report and unveiling of Optimus, Afrinvest’s digital investment app, in Lagos on Wednesday night.
The occasion also marked the announcement of Afrinvest’s new subsidiaries and expansion of its leadership team as well as the unveil of Afrinvest’s refreshed logo(brand identity).
The report’s assessment of CBN’s financial stability indicators showed that Industry Liquidity(Liquidity Ratio) and Non-Performing Loan ratios both improved by 130 basis points(up) and 75bps(down), respectively, to 42.6 per cent and 4.95 per cent. Although, the Capital Adequacy Ratio(CAR: 14.1 per cent) underperformed the June 2021 level by 140bps, all the indicators beat the prudential guideline limits of 30 per cent(LR), five per cent(NPLs), and 13.0 per cent(CAR), respectively, despite myriads of challenges in the business environment.
The report said the improvement is expected to be sustained over the coming years.It explained that the fiscal challenges presented by weak Federal Government earnings have contributed to the muddling of monetary policy and strong use of Cash Reserve Ratio debits as a subtle strategy, in our view, to compensate for the inflationary effect of ballooned overdraft to the government.
It insists that in increasing its developmental financing role, especially in agriculture financing, the CBN risks crowding out banks and private sector financing, which is more effective in de-risking the sector and incentivising growth without moral hazards.
“Importantly, the weak economic growth has robbed banks of the dividend of large and youthful demographics. Over the last 10 years to 2021, real Gross Domestic Product has grown by a compound annual growth rate (CAGR) of 1.9 per cent compared to 2.3 per cent CAGR for the population. In line with the decline in income level, poverty has risen to 40.1 per cent based on national standards of annual real per capita expenditure threshold of N137,430.”
“For banks, this reality means that upscaling would be less efficient than in an economy where growth exceeds population expansion. Not surprising, Nigeria’s financial depth is weak as is for countries with high fertility rates and a fragile economic base,” it said.
To turn the tide, the BSR recommended that critical reforms be undertaken as matter of urgency to avoid a repeat of the negative trends seen in the last decade. “Some other measures advised include the tapering of fiscal deficit financing – credit to the government – to check money supply expansion, alignment of rates across windows and the adoption of market reflective forex rate via the crawling peg regime. We believe that the outcome for banks in the coming decade would rely on the policy actions taken today to address the issues raised,” it said.
On exchange rate management, the report said CBN’s strategy (differentiated rates across market segments and capital control) failed the litmus test over the reviewed period, as anticipated in the 2021 report. It said the value of the Naira depreciated further by 5.6 per cent and 23.2 per cent to N436.50/$1.00 and N712.00$1.00 (on 19/09/2022) at the NAFEX window and parallel market, respectively.
It sated that near-term improvement in the exchange rate is not in sight, given forex supply constraints due to the self-inflicted injuries in Nigeria’s oil & gas sector (the largest source of FX accretion). On the economy, the report said that in 2021, the Nigerian economy recovered markedly from the pandemic-induced strain of the prior year. “Real Gross Domestic Product (GDP) grew 3.4 per cent (2020: -1.9 per cent), beating our projection by 0.4ppts.
The recovery was mainly driven by the expansion of activities in the non-oil sector (up 4.4 per cent), while the oil sector remained in a recession. This growth momentum was sustained into 2022 albeit with a wider divergence between the oil and non-oil sectors.,” it said.
The report stated that, given the resilient half-year 2022 performance and expectation of sustained positive performance by key non-oil activity sectors in third and fourth quarters of the year, it reviewed the 2022 baseline growth forecast upward by 40bps to 3.3 per cent.
However, it maintained that growth momentum in the medium term would remain short of the level that can meaningfully lift the average well-being of the citizenry due to persistent domestic and external headwinds.
It said oil price level, domestic inflation rate has remained persistently high, averaging 14.3 per cent in the last six years. In first half of 2022, headline inflation averaged 16.7 per cent owing to the impact of the Russia- Ukraine war on input prices, continued forex illiquidity, and structural challenges.
Based on the World Bank estimate, the stinging fang of the elevated price level would drag five million more Nigerians into extreme poverty (to reach 95.1m) by 2022 year-end. The report suggested that only concerted fiscal and monetary policy efforts targeted at resolving insecurity challenges, optimising exchange rate management, fixing structural loopholes, and curbing reckless fiscal spending would resolve the high inflation quagmire.
It however, acknowledged that the CBN has taken the lead in the efforts at curtailing the runaway inflation rate as seen in the back-to-back hike of the Monetary Policy Rate in May, July, and September 2022 to 15.5 per cent.
On the fiscal policy front, it said the divergence between the share of FG’s recurrent (debt & non-debt combined) and capital expenditure component has widened significantly in the last decade.
“Sadly, economic growth and fiscal stability have suffered the biggest impact from the worsened divergence. Before then, we observed a strong nexus between capital expenditure performance and growth in the decade to 2009. From 1999 to 2009, the divergence between the size of recurrent and capital expenditure averaged 48.5 per cent,” it stated.
It explained that over this period, GDP growth (average: 7.0 per cent) out- paced population growth (2.6 per cent p.a.) significantly. This trend dovetailed into a strong labour market perfor- mance as the unemployment rate eased steadily to about 5.0 per cent by 2009 year-end, according to NBS data. Also, GDP per capita surged by 279.9 per cent to $1,891, while fiscal condition ended the decade strong as FG revenue to expenditure ratio printed at 76.5 per cent (2009) with public debt stock (N3.8tn) to GDP ratio of 7.5 per cent.
Sadly, this trend has completely reversed over the last decade. It explained that between 2010 and 2021, the divergence between the share of recurrent and capital expenditure budgets widened to 74.3 per cent on average. “As a result, the share of capital expenditure in the total budget has dropped to an average of 18.9 per cent per annum.
When examined from 2015, the divergence is wider at an average of 75.3 per cent, while the average share of capital expenditure in the total budget printed lower at 18.5 per cent This suggests that the economy’s average propensity to consume (represented by recurrent expenditure) has increased by more than 20.0 per cent in the last decade,” the report said.
In his comments, the Group Managing Director, Afrinvest West Africa, Ike Chioke, said Nigerians should prepare for reforms that would turn the economy around.He said that looking ahead, Nigeria was set for another cycle of leadership in 2023 as the tenure of President Muhammadu Buhari, 30 state governors, and over 1,000 legislatures draw to a close.
“At a time when there is daunting fiscal, monetary, and social challenges to surmount, Nigerians cannot afford to elect leaders who lack the competence, capacity, and creativity to find lasting solutions to the national quagmire. Even with a leadership that is willing to introduce the needed reforms, the present challenging environment would worsen before it can get better,” Chioke said.According to the him, regardless of who the President is, Nigerians will need to brace for impact.
“Noteworthy, the political will of the incoming administration to implement tough reforms that would curtail major economic leakages such as the subsidy regime on PMS(which has gulped over N7.0tn since 2010) and ensure the proper channelling of scarce resources to critical sectors would be a refreshing start,” he added.

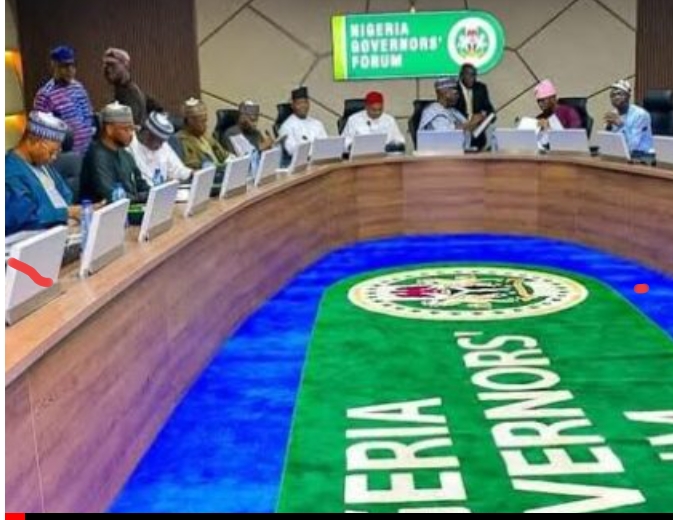


• Says economic reforms have placed Nigeria on recovery path
• Shettima insists economy would have collapsed without tough decisions
President Bola Tinubu has declared that his administration has no regrets over the removal of petrol subsidy, insisting that Nigeria will never return to the old subsidy regime despite criticisms from political opponents.
Tinubu made the declaration on Monday evening at an event tagged Together Till 2027: An Evening with Original City Boy, organised by the City Boy Movement in collaboration with the Relax-Tinubu-Is-Fixing-Nigeria movement.
Defending his decision to remove fuel subsidy on May 29, 2023, the President said Nigeria was heading towards bankruptcy when he assumed office, stressing that the country could no longer sustain the financial burden.
Drawing an analogy from the biblical account of Moses leading the Israelites out of Egypt, Tinubu said returning to the subsidy regime would amount to reversing Nigeria’s journey towards economic recovery.
“You cannot ask Moses to go back to Egypt. We wake up with ideas, original thoughts, and deep thinking to move this country forward. With your energy, your support, Nigeria will never go back to Egypt. No regrets,” he declared.
The President also took a swipe at his political opponents, particularly former Vice President Atiku Abubakar, who had proposed restoring a modified petroleum subsidy arrangement if elected in 2027.
Tinubu maintained that his administration inherited enormous economic challenges, including depleted foreign reserves, outstanding obligations to foreign airlines and unsustainable government borrowing.
He explained that rather than dwell on the shortcomings of the previous administration, he accepted responsibility for addressing the country’s economic difficulties.
According to him, the difficult decisions taken by his government have begun yielding positive results, with the economy recording steady growth.
Turning to the 2027 presidential election, Tinubu urged young Nigerians to mobilise support for his administration and ensure that eligible voters obtain their Permanent Voter Cards.
He maintained that the forthcoming election should be about securing the country’s future rather than advancing the personal ambition of any candidate.
“You are not campaigning for me. You are campaigning for your own future, and that future is Renewed Hope,” he stated.
The President also defended the Students Loan Act, revealing that more than one million students had benefited from the Nigerian Education Loan Fund, NELFUND.
He commended his son, Seyi Tinubu, and members of the City Boy Movement for mobilising young Nigerians, urging them to intensify their grassroots engagements ahead of the election.
Speaking earlier, Vice President Kashim Shettima insisted that Nigeria’s economy would have collapsed without the far-reaching reforms introduced by the Tinubu administration.
Shettima argued that the President demonstrated courage by implementing difficult policies at a time when the country’s economic outlook was increasingly uncertain.
He cited economic growth of 4.43 per cent in the last quarter and foreign reserves reportedly approaching $60 billion as evidence of the administration’s progress.
Acknowledging the hardship experienced by Nigerians, the Vice President maintained that the situation could have been worse without the government’s intervention.
He also assured Nigerians that the administration was preparing measures to address agricultural challenges and bring down food prices.
“The President has to be commended, not demonised. Yes, Nigerians have gone through some tough times, but it could have been worse,” Shettima said.
In his remarks, Deputy Senate President Barau Jibrin described the City Boy Movement as a technology-driven political organisation capable of strengthening Tinubu’s reelection campaign.
He urged the group to deploy artificial intelligence in communicating the President’s policies, achievements and political philosophy while responding to opposition narratives.
Similarly, Speaker of the House of Representatives, Tajudeen Abbas, called on political officeholders to present verifiable accounts of projects and interventions delivered under the Tinubu administration.
Abbas disclosed plans to publish an audit of federal government interventions in his Zaria constituency within 14 days, challenging other public officeholders to demonstrate what they had achieved for their constituents.
He urged the City Boy Movement to independently verify government projects and provide feedback from ordinary Nigerians.
Earlier, the Director-General of the movement, Francis Shoga, assured Tinubu that Nigerian youths were prepared to mobilise nationwide in support of his Renewed Hope agenda.
Shoga described members of the organisation as committed partners in the administration’s national transformation programme, pledging to take its message to communities across the country.
Tinubu’s latest declaration comes amid continuing debate over the economic consequences of fuel subsidy removal, which triggered sharp increases in petrol prices and contributed to rising living costs across Nigeria.
By Francis Onoh
It is the right of every Nigerian to be financially included in the system. Data from the country’s foremost financial institution, the Central Bank of Nigeria (CBN) and the organisation Enhancing Financial Innovation and Access show that approximately 40% of Nigerians adults are financially excluded.
Attaining the 3.4% projected growth in the economy’s GDP will be difficult if not impossible, if the petty traders, the local skill workers and the roadside sellers are excluded from financial services and products that can aid their businesses. Enhancing financial inclusion for economic growth requires that financial literacy be extended and incorporated into the activities of organisations that work at the grassroots, for example, religious institutions.
Although with low levels of literacy, Emeka, Haruna or Bankole as devoted adherents of their various religions, are more likely to understands that their money is secure in the financial sector, that products such as pension plan, health insurance schemes and access to credit are available for citizens who are financially included, if and only if leaders of their religion introduce financial literacy to them. Combining their obligation to teach articles of their faith with introducing their members to financial literacy is one way to go if our country has to remedy the financial exclusion created by poverty and limited access to formal education.From the Global Multidimensional Poverty Index, the dimensions of poverty are Health, Education and Standard of Living.
Access to financial services can encourage people to enrol in a health insurance scheme to ensure good health within a manageable expenditure. A financially included person will have formal or informal education by association, which will invariably improve the living standard.
A financially included person is more likely to increase their business share if they access credit facilities in the financial sector and stand a better chance to benefit from government poverty alleviation programmes or even access funds from international development.
Making about 40% of Nigerian adults, which is about 35 million people, financially included will enhance capital formation assets, improve citizens’ disposable income, grow the nation’s financial sector and in extension catalyse industrialisation, which the country direly needs at this time. Financial inclusion for all is a necessary good that should be pursued by the Nigerian government at all levels, and stakeholders, such as religious leaders, must be made aware of their obligation in this space.
The time to do this is now.
Francis Onoh writes from Enugu
The Bank gave this warning on Monday during the public presentation of its latest Nigeria Development Update report titled ‘Building Momentum for Inclusive Growth’ in Abuja.
President Bola Tinubu signed the 2025 Appropriation Act into law, approving a record budget of N54.99tn, the highest in Nigeria’s history.
The budget was raised from the initial proposal of N49.7tn submitted to the National Assembly.
The fiscal plan makes provisions for N13.64tn in recurrent expenditure, N23.96tn for capital projects, N14.32tn for debt servicing, and N3.65tn for statutory transfers, while projecting a deficit of N13.08tn, to be financed through domestic and external borrowing.
The budget assumptions include a crude oil benchmark of $75 per barrel, oil production at 2.06 million barrels per day, an average exchange rate of N1,400/$, and an inflation target of 15 per cent.
Speaking at the event, the World Bank’s Lead Economist for Nigeria, Mr Alex Sienaert, said that despite strong revenue gains recorded in 2024, Nigeria’s 2025 budget assumptions remain optimistic and may prove difficult to meet.
He said, “It’s a very ambitious budget. Even with the very positive revenue sort of tailwind that we have… even considering that, it looks like it’s going to be pretty hard to meet some of the ambitious revenue targets that are in there.”
According to him, key assumptions such as average daily crude oil production of 2.1 million barrels per day and a benchmark oil price of $75 per barrel are unlikely to hold, noting that current production figures are closer to 1.6 million barrels per day.
He also cited uncertainty over how much revenue would flow from the removal of the petrol subsidy and the planned windfall tax on foreign exchange gains, saying these could weaken the Federal Government’s revenue position.
“This is important because if it does turn out that the revenue targets are not met, then that could mean that the financing requirements are more than budgeted. And if the financing requirements exceed what’s budgeted, then that’s either going to create arrears pressures… or it could renew risks of recourse to things like deficit monetisation under large-scale Ways and Means,” he said.
Sienaert warned that although Nigerian authorities had pledged not to resort to the CBN’s overdraft facility, doing so again could derail the country’s fragile macroeconomic recovery.
“The authorities have been very clear that they will by no means be going back to large-scale use of Ways and Means, but were that to happen, it would be just extremely disruptive to the whole rebuilding of confidence in fiscal sustainability and in the naira ultimately,” he noted.
On broader fiscal matters, the World Bank called on the Federal Government to eliminate the electricity subsidy, which it described as a “wasteful, regressive subsidy.”
Sienaert said key fiscal reforms such as the removal of the petrol subsidy and the adoption of a market-reflective exchange rate had helped improve the government’s fiscal position, but further reforms were needed.
“There’s still a range of fiscal policy and fiscal management issues where more can be done to safeguard the gains that have already been achieved… just to name, there is still one kind of wasteful regressive subsidy, which is the electricity subsidy. So work to address that,” he said.
He also advocated for improved oil revenue transparency and a reduction in the cost of governance, saying efforts to increase non-oil revenue must continue.
Sienaert noted that although the Nigerian National Petroleum Company Limited began applying official exchange rates for fiscal transactions in October 2023, only half of the revenue gains from the subsidy removal had been remitted to the Federation Account by January 2025.
“It’s just going to be important in the coming months to keep tracking this, and ultimately that the full revenue gains from the difficult job of eliminating the subsidy do flow to the Federation so that that can support a continued healthy fiscal picture and, in turn, spending on development priorities,” he said.
On inflation, the World Bank economist said monetary policy reforms had helped reduce inflationary pressures but noted that consumer prices remained high.
“We do need to acknowledge that price pressures remain elevated,” he said. “The battle against inflation continues, and to extend the military analogy a little bit, there’s a kind of fog of war… quite dense just at the moment.”
He added that recent changes to the Consumer Price Index by the National Bureau of Statistics had made it difficult to determine the current trend in inflation, noting, however, that continued coordination between fiscal and monetary authorities would be critical to restoring confidence.
The World Bank further urged the government to ramp up implementation of its targeted cash transfer programme aimed at cushioning the cost of reforms on poor households. The programme currently offers N25,000 monthly for three months to 15 million recipients.
“The implementation has just been quite slow. So only about a third of those recipients have received transfers so far. The good news is that this is being scaled up… and just important that that effort really continues so that as many people as possible get help,” Sienaert said.
Looking ahead, he called for a new growth strategy based on a “private-led, public-facilitated” model.
The World Bank also stressed the need to reduce costs of governance, including cutting “wasteful expenditures that are not essential, such as purchase of vehicles, external training, etc.” and reducing “the cost of collection of GOEs (FIRS, NCS, NMDPRA, NUPRC, etc.).”
He emphasised the need for increased investment in education and health, noting that Nigeria’s combined spending in these sectors remained among the lowest globally.
“In 2022, Nigeria was only spending 1.2 per cent of GDP on education and 1.8 per cent on health, or $23 per Nigerian per year on education, $15 per Nigerian per year on health,” he said.
He said private sector growth must also be supported by improving the competitive landscape and reviewing trade policies that restrict access to essential production inputs.
“Competition is like the sort of secret sauce that drives innovation and economic transformation. And in Nigeria, there’s some evidence… that actually there are elements of competition policy, and there are conditions that are needed for good competition that actually even compared to some of Nigeria’s immediate peers… the Nigerian competitive landscape lags some of those,” he said.
The Bank believes that following through with these reforms will position Nigeria to achieve its goal of becoming a $1tn economy by 2030.
The Naira depreciated to N1,600 per dollar in the Nigerian Foreign Exchange Market (NFEM) today after three months of being on the N1,500 per dollar threshold.
Data published by the Central Bank of Nigeria, CBN, showed that the indicative exchange rate for the naira rose to N1,600 per dollar from N1,569 per dollar on Thursday, indicating N31 depreciation for the naira.
Likewise, the naira depreciated to N1,565 per dollar in the parallel market from N1,555 per dollar on Thursday.
Consequently, the margin between the parallel market and NFEM rate widened to N35 per dollar from N14 per dollar on Thursday.
Vanguard News
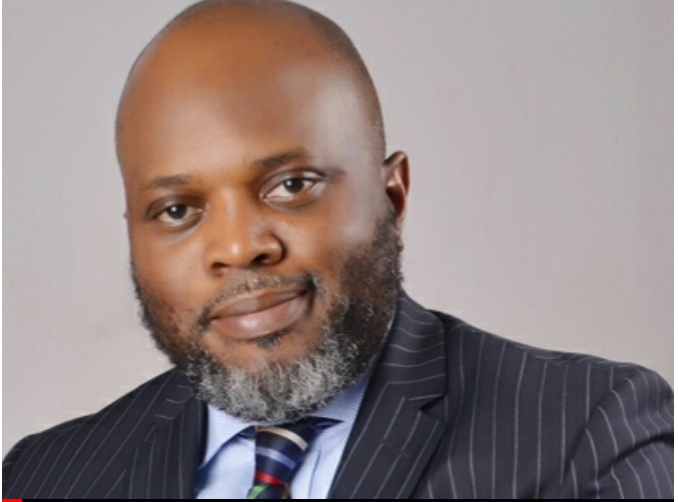
Fasua, who spoke on the Mic On Podcast hosted by Seun Okinbaloye on Saturday, also addressed how poverty is measured globally, saying many Nigerians misunderstand what is termed “multi-dimensional poverty.”
He said, “Some people don’t understand the meaning of multi-dimensional poverty.
“They think multi-dimensional poverty is worse than food poverty. What multi-dimensional means is that maybe the school your children attend is too far from you, or the hospital, and they categorise you as multi-dimensional.”
“$1 is N1,500 – it’s a lot of money for many people in Nigeria. $10 won’t buy you lunch anywhere in the US, sometimes you need at least $20, that is N30,000 in Nigeria,” Fasua stated.
Offering examples from everyday life, Fasua added, “I will tell you what you can do with $5 – that is N7,500 – if you are not going to eat in some highbrow places. In Gwarinpa, there are some people that sell Boli and fish and you will eat for N1,500. If you know where you are coming from.
-
 News3 days ago
C’RIVER 2027 BUDGET: GOV OTU PRESENTS ₦987.8bn ESTIMATES TO ASSEMBLY
-
 EverydayNews Telescope3 days ago
Enugu East Senate: The Dark Side of Ada Ogbu, NDC Candidate
-
 Opinion5 days ago
Christian Chinyeaka Ohaa: THE BUTTERFLY THAT THINKS IT’S A BIRD!
-
 News4 days ago
Tension Mounts in Awka Anglican Diocese as Supervising Bishop Ezeofor Moves to Take Over Wednesday
-
 News2 days ago
Holy Ghost Transformation: How Enugu North Chairman Ibenaku Onoh Ended Years of Traffic Chaos, Roadside Trading
-
News5 days ago
Awka Anglican Diocese Rejects Primate’s Six-Month Suspension of Archbishop Ibezim, Threatens Exit
-
 EverydayNews Telescope3 days ago
Ebonyi 2027: The People’s Quest For ODII Vs Compromised Stakeholders
-
News5 days ago
We Are Fighting Principalities, Spiritual Forces, Not Flesh and Blood – Archbishop Ibezim